- Car Loans
- Home Loans
- Personal Loans
- Business Loans
- Helpful Resources
-
-
- Loan Calculators ❯ Get My FREE Property Report ❯ Get My Credit File ❯ Send My Bank Statements ❯ Blog ❯ Personal Loan calculator
-
-
Why Keeping Your Home Loan Repayments the Same When Rates Go Down, Makes Perfect Sense
By Mary Nebotakis, Managing Director, Natloans, B. Eco, Dip. Financial Services
How You Can Pay Off Your Loan Sooner and Save Thousands
On February 19, 2025, the Reserve Bank of Australia (RBA) made a crucial decision to reduce the official cash rate by 0.25%. For many Australian homeowners, this means their mortgage interest rates will also decrease. While the natural reaction might be to reduce repayments and enjoy extra cash flow, there’s a smarter move that could save you years on your loan and tens of thousands of dollars in interest.
By keeping your repayments at the same level despite the rate cut, you can dramatically shorten your loan term and build equity faster. Let’s break it down with real numbers.
The Power of Keeping Your Repayments Steady
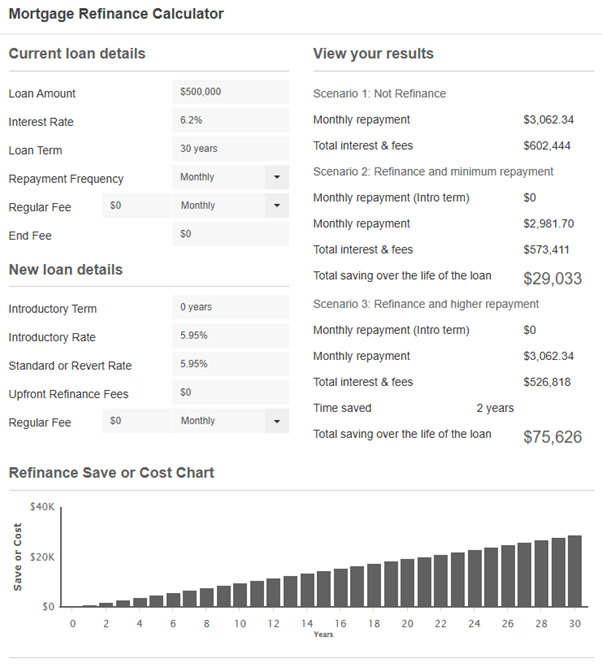
Imagine you have a $500,000 home loan with a 30-year term at an interest rate of 6.25% per annum. Before the rate cut, your monthly repayment would be approximately $3,062.
Now, after the RBA’s 0.25% rate reduction, your lender lowers your interest rate to 5.95% per annum. If you chose to reduce your repayments in line with this new rate, your new monthly payment would be lower.
But here’s where the magic happens: instead of lowering your repayments to the new minimum monthly repayment of $2,982, you keep them the same at $3,062 per month.
Note: The information provided by the calculator is intended to provide illustrative examples based on stated assumptions and your inputs. Calculations are meant as estimates only and it is advised that you consult with a mortgage broker about your specific circumstances. Financial Calculators © Vision Abacus Pty Ltd 2025
The Results
By keeping your repayments unchanged, you would:
- Pay off your mortgage 2 years sooner
- Save approximately $75,000 in interest over the life of the loan
That’s two years of mortgage-free living and a massive reduction in interest costs – all without spending a cent more than you already budgeted for!
Why This Strategy Works
This approach works because your extra payments directly reduce the principal balance of your loan, rather than just covering interest. As a result:
- More of your payment goes toward the loan itself – shrinking your balance faster.
- You reduce the overall amount of interest paid, since interest is charged on a smaller balance over time.
- You build home equity faster, giving you more financial flexibility down the track.
The Bigger Picture: Long-Term Financial Benefits
- Less financial stress later on – The sooner you pay off your mortgage, the more financial freedom you’ll have in retirement.
- More borrowing power – A smaller loan balance improves your credit position if you ever need to refinance.
- Flexibility when needed – By getting ahead on your loan, you create a buffer in case of unexpected financial changes. Extra repayments can then be accessed through available redraw
What Should You Do Next?
If you’re unsure whether this strategy is right for you, or you’d like to explore other ways to get ahead on your home loan, Natloans can help.
Our expert mortgage brokers can:
- Assess your current home loan and help you optimise your repayments
- Compare refinancing options to ensure you’re getting the best deal
- Develop a plan to help you become mortgage-free sooner
Take Action Today
With interest rates dropping, now is the perfect time to take control of your financial future. Contact Natloans today to discuss your options and start making the most of lower rates!
PrevWhat Are Private Mortgages and How Do They Work? Stamp Duty Abolished on New Homes for Eligible First Home Buyers in Queensland: What It Means for YouNextCategories
https://www.natloans.com.auWant a tailored finance solution?
Contact Us Car Loans- Personal Car Loans
- Business Car Loans
- Chattel Mortgage
- Electric Vehicle Loans
- Low Doc Car Loans
- Finance Lease
- Bad Credit Car Loans
- Car Loan Refinancing
- Sale & Leaseback Finance
- Novated Car Lease
- Low Rate Personal Loans
- Debt Consolidation
- Home Renovation Loans
- Bike Loans
- Boat Loans
- Caravan Loans
- Jet Ski Loans
- Green Loans
- Medical, Cosmetic & Dental Loans
- Buy A New Home
- Refinance My Home Loan
- Buy an Investment Property
- First Home Buyers
- Low Doc Home Loans
- Construction Loans
- Apply For a Home Loan Now
- Low Doc Business Loans
- Truck Finance
- Equipment Finance
- Business Overdraft
- Commercial Property Finance
- Private Lending
- SMSF Commercial Loans
- Working Capital Finance
- Melbourne Mortgage Brokers
- Sydney Mortgage Brokers
- Brisbane Mortgage Brokers
- Adelaide Mortgage Brokers
- Darwin Mortgage Brokers
- Perth Mortgage Brokers
- Hobart Mortgage Brokers
- Melbourne Finance Brokers
- Sydney Finance Brokers
- Brisbane Finance Brokers
- Adelaide Finance Brokers
- Perth Finance Brokers
- Darwin Finance Brokers
- Hobart Finance Brokers
Want a tailored finance solution?
Contact Us- Call Us
- Email Us
- Text Us
- Visit Us
7/296 Bay Rd
Cheltenham VIC 3192
Natloans is part of the Natloans group of companies, proudly owned by Natloans Holdings Pty Ltd. All services delivered under the Natloans brand are provided by licensed entities within our group — and we’ll always confirm the relevant entity in your documentation for complete transparency.
Images on This Page
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-white-logo.webp
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/natloans_logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-person.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-money-case.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-money-bag.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_electric-car-rounded.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_edit-document.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/solar_chat-round-money-bold.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_credit-card.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-calculator.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-service.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-bank.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/ic_round-home.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-dollar.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-first.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-construction.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-saving.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-trending-down.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-bike.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-boat.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-caravan.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-jet-skiing.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-solar-eclipse.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-truck.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/ic_baseline-business-center.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/bxs_bank.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/09/icon-blog-notes.svg
Blog
-
https://www.natloans.com.au/wp-content/uploads/2025/04/image-17-150x150.png
Picture of By Mary Nebotakis, Managing Director, Natloans, B. Eco, Dip. Financial Services
-
https://www.natloans.com.au/wp-content/uploads/2025/02/Calculator-Picture-for-Blog.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/02/iStock-2155118444.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/NL0426-02_Awards_HORIZONTAL-scaled.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-awards.png
(no alt text)