- Car Loans
- Home Loans
- Personal Loans
- Business Loans
- Helpful Resources
-
-
- Loan Calculators ❯ Get My FREE Property Report ❯ Get My Credit File ❯ Send My Bank Statements ❯ Blog ❯ Personal Loan calculator
-
-
Financing Your Next Home Upgrade in Sandringham
By Mary Nebotakis, Managing Director, Natloans, B. Eco, Dip. Financial Services
As property values continue to evolve across Melbourne’s Bayside region, many homeowners in Sandringham are finding themselves at an important decision point: renovate their current home, or upgrade to a larger property that better suits their future needs.
Whether you’re looking for additional bedrooms, a dedicated home office, more outdoor space, or a long-term family home, upgrading can be an exciting opportunity. However, purchasing a larger property often requires careful planning, particularly when it comes to borrowing capacity, home loan options, and accessing existing equity.
This guide explores some of the key financial considerations Sandringham homeowners may wish to review when planning their next move.
Engaging a knowledgeable Mortgage Broker in Sandringham can provide valuable insights and access to a range of financing options suitable for your needs. Additionally, understanding local market trends can help you make informed decisions.
Why Homeowners Are Upgrading in Sandringham
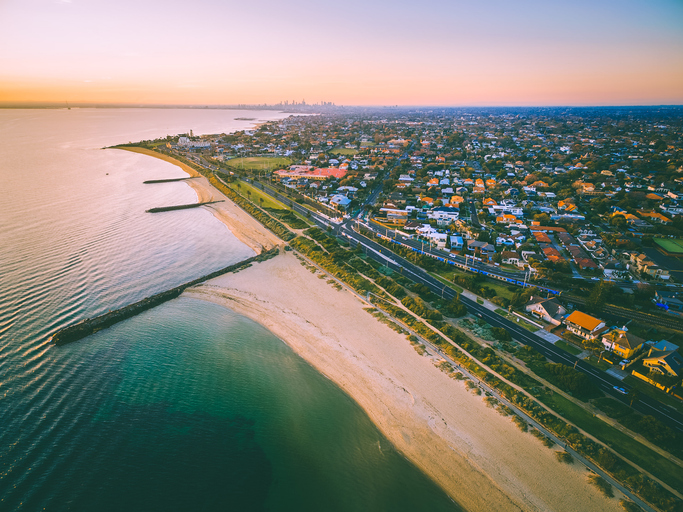
Sandringham remains one of Melbourne’s most desirable Bayside suburbs, attracting families, professionals, and long-term owner-occupiers seeking a premium coastal lifestyle.
With its beaches, schools, transport connections, shopping precincts, and strong community atmosphere, many residents prefer to remain within the Bayside area rather than relocate elsewhere.
Common reasons homeowners choose to upgrade include:
- Growing families requiring additional bedrooms
- Increased demand for work-from-home spaces
- Lifestyle changes and entertaining requirements
- Larger outdoor areas for children and pets
- Moving closer to schools, parks, and amenities
- Purchasing a long-term family home
For many Bayside homeowners, upgrading allows them to remain in a location they already love while securing a property that better aligns with their future plans.
Understanding Your Borrowing Capacity
Before searching for a larger property, many buyers choose to review their borrowing position with a mortgage broker.
Lenders generally assess factors such as:
- Employment and income
- Existing loans and liabilities
- Household expenses
- Available savings
- Property equity
- Credit history
Understanding borrowing capacity early may help establish realistic expectations around property budgets and purchasing opportunities.
A mortgage broker can also help compare lending policies across multiple lenders, as borrowing calculations can vary significantly between institutions.
Using Home Equity to Upgrade
For homeowners who have owned property for several years, accumulated equity may become an important part of the upgrade process.
Home equity generally refers to the difference between your property’s current market value and the outstanding balance of your mortgage.
Depending on individual circumstances, available equity may potentially assist with:
- Deposits on a new property
- Stamp duty and purchasing costs
- Renovations after settlement
- Reducing upfront cash requirements
Property values across Sandringham and neighbouring Bayside suburbs have changed considerably over time, leading many homeowners to review how much usable equity may be available.
Selling Before Buying vs Buying Before Selling
One of the most common questions mortgage brokers receive from upgrading homeowners involves timing.
Selling Before Buying
Selling your existing property first may provide greater certainty around available funds and borrowing requirements.
Potential advantages may include:
- Clear understanding of available equity
- Reduced exposure to holding two properties simultaneously
- Greater confidence when setting a purchase budget
However, temporary accommodation may sometimes be required if settlement dates do not align.
Buying Before Selling
Purchasing before selling may allow homeowners to move directly into their new property.
Potential considerations include:
- Managing two properties during the transition
- Additional borrowing requirements
- Coordinating settlement timeframes
- Potential cash-flow implications
The most suitable approach will depend on individual circumstances, financial objectives, and market conditions.
What Is Bridging Finance?
Bridging finance is a common solution explored by homeowners purchasing a new property before selling their existing home.
A bridging loan may provide temporary funding during the transition period, helping borrowers secure their next property before their current property settles.
Because bridging finance structures can vary between lenders, many homeowners choose to seek guidance from a mortgage broker when comparing available options.
Factors that may be considered include:
- Loan structure
- Interest costs
- Loan term
- Exit strategy
- Property values
- Borrowing capacity
Costs to Consider When Upgrading
When planning a property upgrade, it is important to budget for costs beyond the purchase price itself.
Potential expenses may include:
- Stamp duty
- Conveyancing and legal fees
- Building and pest inspections
- Moving costs
- Loan establishment fees
- Property valuation fees
- Lenders Mortgage Insurance (where applicable)
Understanding these costs early can help provide a clearer picture of the overall budget required.
Fixed, Variable and Split Home Loan Options
When upgrading to a new property, homeowners may also wish to review their home loan structure.
Fixed Rate Loans
Fixed-rate loans may provide repayment certainty over an agreed period.
Variable Rate Loans
Variable-rate loans may offer greater flexibility, including features such as offset accounts and redraw facilities.
Split Loans
Split loans combine fixed and variable components within the same mortgage, allowing borrowers to balance certainty and flexibility.
A mortgage broker can help explain the differences between these options and compare how various lenders structure their products.
Why Work With a Mortgage Broker in Sandringham?
Upgrading a home often involves multiple moving parts, including borrowing assessments, equity calculations, property sales, loan approvals, and settlement coordination.
Many homeowners choose to work with a mortgage broker because it can simplify the process of comparing lenders and navigating finance options.
Rather than approaching lenders individually, a mortgage broker can help compare multiple loan products, interest rates, and lending policies from a broad panel of lenders.
For homeowners throughout Sandringham, Brighton, Hampton, Black Rock, Cheltenham, Mentone and the wider Bayside region, local knowledge can also be valuable when planning an upgrade.
Why Bayside Homeowners Choose Natloans
Natloans has helped thousands of Australians secure finance solutions across home loans, refinancing, personal loans and asset finance.
Our mortgage brokers assist homeowners throughout Sandringham and Melbourne’s Bayside suburbs with:
- Borrowing capacity assessments
- Home loan comparisons
- Equity release strategies
- Bridging finance options
- Home upgrades and property purchases
- End-to-end application support
Clients benefit from:
- Access to more than 50 lenders
- Over 750 five-star Google reviews
- More than 15 years of industry experience
- Over 100 years of combined lending expertise
Natloans was also recognised as the Best Finance Brokerage (Office) for Victoria & Tasmania at the Adviser Better Business Awards 2026., reflecting our commitment to delivering exceptional customer service and finance solutions.
Looking to Upgrade Your Home in Sandringham?
If you’re considering upgrading to a larger property in Sandringham or elsewhere in Melbourne’s Bayside region, speaking with a mortgage broker may help you better understand your borrowing position and available home loan options.
Whether you’re exploring equity, comparing lenders, reviewing bridging finance, or preparing for your next property purchase, Natloans can help guide you through the process.
Book a FREE Home Loan Consultation with Natloans today or call 1300 955 791 to speak with an experienced mortgage broker.
PrevWhy Cheltenham Homeowners Are Reviewing Their Mortgages in 2026 A Guide to Buying an Apartment in BrightonNextCategories
https://www.natloans.com.auWant a tailored finance solution?
Contact Us Car Loans- Personal Car Loans
- Business Car Loans
- Chattel Mortgage
- Electric Vehicle Loans
- Low Doc Car Loans
- Finance Lease
- Bad Credit Car Loans
- Car Loan Refinancing
- Sale & Leaseback Finance
- Novated Car Lease
- Low Rate Personal Loans
- Debt Consolidation
- Home Renovation Loans
- Bike Loans
- Boat Loans
- Caravan Loans
- Jet Ski Loans
- Green Loans
- Medical, Cosmetic & Dental Loans
- Buy A New Home
- Refinance My Home Loan
- Buy an Investment Property
- First Home Buyers
- Low Doc Home Loans
- Construction Loans
- Apply For a Home Loan Now
- Low Doc Business Loans
- Truck Finance
- Equipment Finance
- Business Overdraft
- Commercial Property Finance
- Private Lending
- SMSF Commercial Loans
- Working Capital Finance
- Melbourne Mortgage Brokers
- Sydney Mortgage Brokers
- Brisbane Mortgage Brokers
- Adelaide Mortgage Brokers
- Darwin Mortgage Brokers
- Perth Mortgage Brokers
- Hobart Mortgage Brokers
- Melbourne Finance Brokers
- Sydney Finance Brokers
- Brisbane Finance Brokers
- Adelaide Finance Brokers
- Perth Finance Brokers
- Darwin Finance Brokers
- Hobart Finance Brokers
Want a tailored finance solution?
Contact Us- Call Us
- Email Us
- Text Us
- Visit Us
7/296 Bay Rd
Cheltenham VIC 3192
Natloans is part of the Natloans group of companies, proudly owned by Natloans Holdings Pty Ltd. All services delivered under the Natloans brand are provided by licensed entities within our group — and we’ll always confirm the relevant entity in your documentation for complete transparency.
Images on This Page
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-white-logo.webp
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/natloans_logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-person.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-money-case.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-money-bag.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_electric-car-rounded.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_edit-document.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/solar_chat-round-money-bold.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_credit-card.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-calculator.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-service.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-bank.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/ic_round-home.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-dollar.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-first.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-construction.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-saving.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-trending-down.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-bike.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-boat.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-caravan.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-jet-skiing.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-solar-eclipse.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-truck.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/ic_baseline-business-center.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/bxs_bank.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/09/icon-blog-notes.svg
Blog
-
https://www.natloans.com.au/wp-content/uploads/2025/04/image-17-150x150.png
Picture of By Mary Nebotakis, Managing Director, Natloans, B. Eco, Dip. Financial Services
-
https://www.natloans.com.au/wp-content/uploads/2026/06/iStock-693956278.jpg
Mortgage Broker in Sandringham
-
https://www.natloans.com.au/wp-content/uploads/2026/04/NL0426-02_Awards_HORIZONTAL-scaled.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-awards.png
(no alt text)